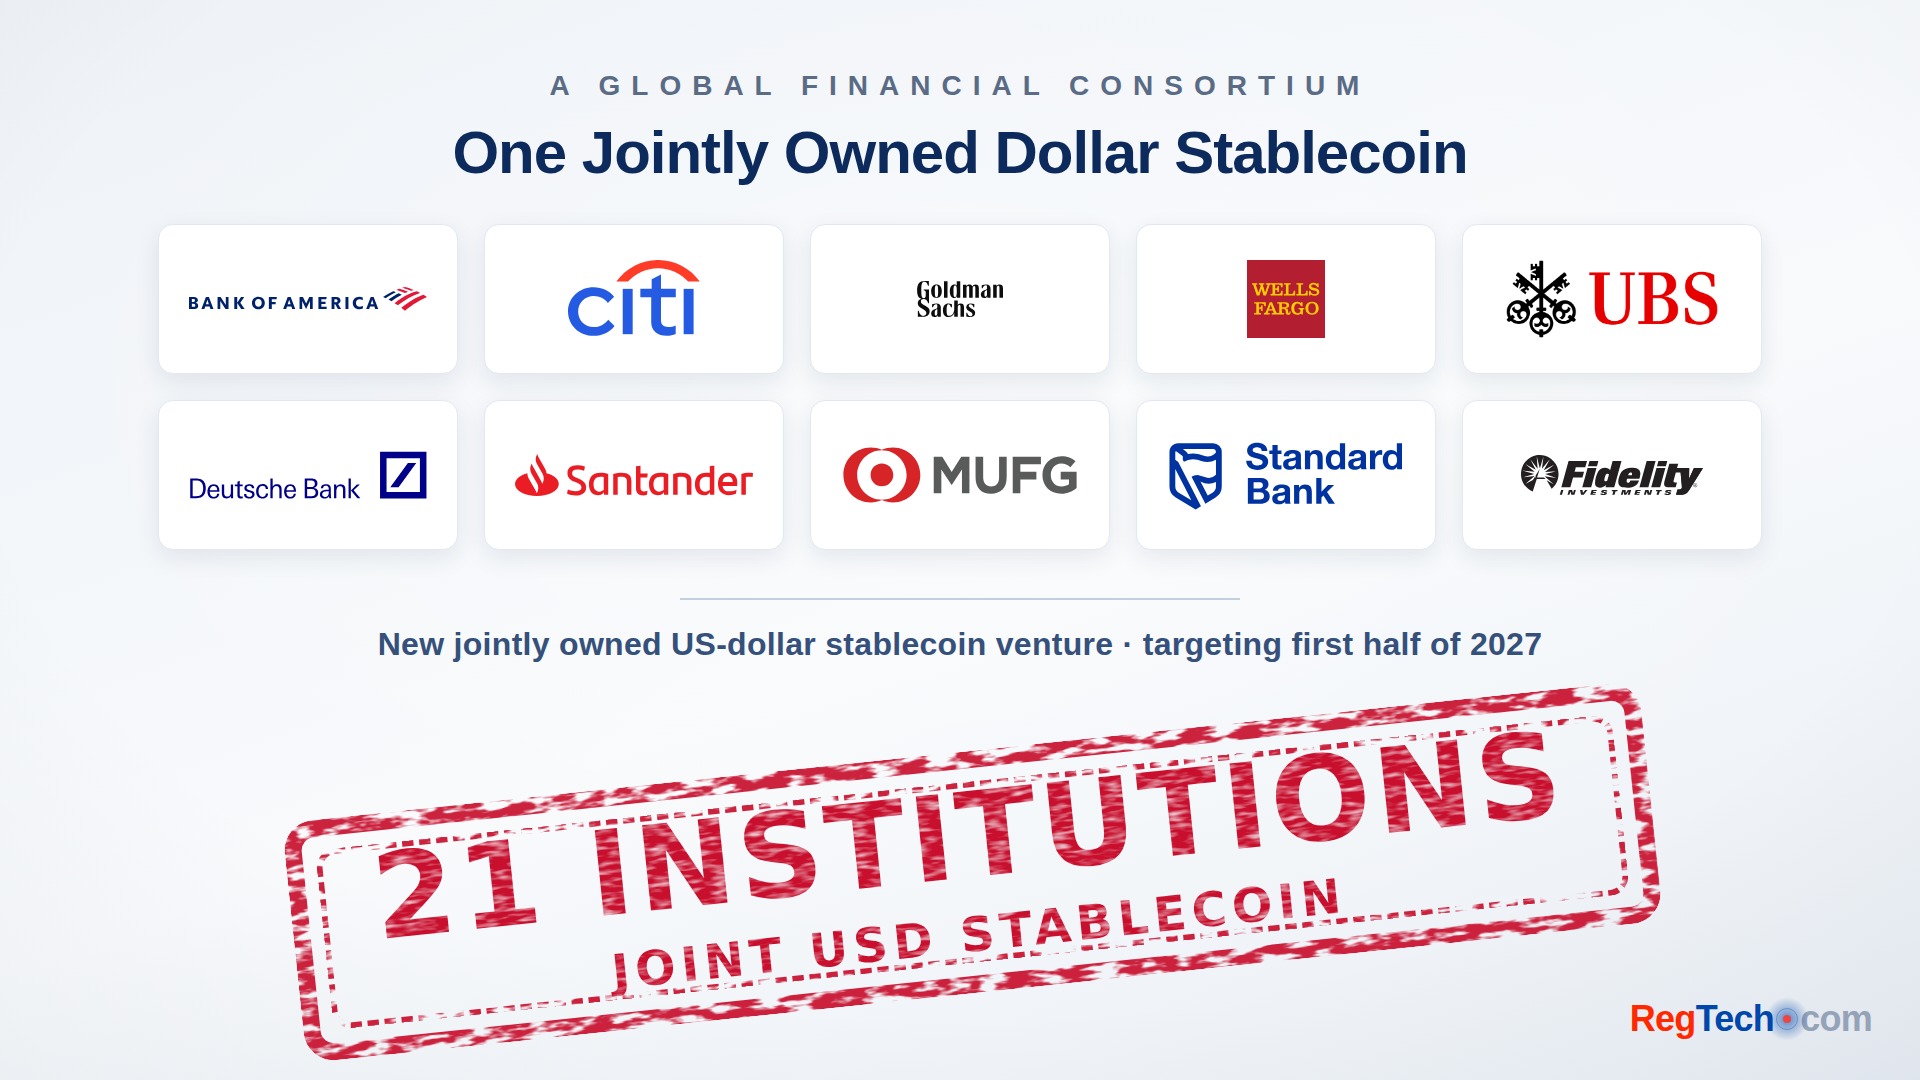
21 of the world's largest financial institutions, including major banks, asset managers, and a holding company, have agreed to build a stablecoin together. The group set this out in a joint statement issued on 1 September 2026, which participating bank MUFG published on its own newsroom the following day. The statement said the institutions would establish a new company to support the issuance of a US dollar-denominated stablecoin, with the coin targeted to reach the market in the first half of 2027.
The line-up is unusually broad for a single venture. It spans Bank of America, Citi, Goldman Sachs, Wells Fargo, Capital One, PNC Financial Services, Scotiabank, TD Bank Group, Fidelity Investments and WisdomTree in North America; UBS, Deutsche Bank, Banco Santander, BBVA, Commerzbank, Crédit Agricole, Lloyds Banking Group and Rabobank in Europe; Japan's MUFG Bank; the United Arab Emirates' Sirius International Holding; and South Africa's Standard Bank. Notably, the group is not exclusively banks: it includes asset managers and a holding company, which matters for how regulators will oversee the venture.
What has actually been committed
The announcement commits to forming a company, not launching a live product. The new entity has not yet been named and is slated to be set up in the second half of 2026 once the usual completion conditions are met, ahead of the coin's own launch in 2027. The statement names two firms in a supporting role: Boston Consulting Group on the business side and Brunswick Group on communications. The statement includes an explicit disclaimer that both act solely as advisers and have no authority to bind the consortium or any of its members.
The plan builds on an earlier, more tentative step: in October 2025, ten banks first explored issuing a fully reserve-backed digital currency that could settle over public blockchains. That exploration has now become a formal commitment, and membership has more than doubled. A comparable industry-owned effort is already under way in the United States, where 39 state bankers associations have come together to build the BankChain Alliance on a similar 2027 timeframe.
The institutions describe the coin as global in scope. In the consortium’s own framing, the coin is meant to support “cross-border payments and digital asset settlements” for customers that range from individual consumers to the largest institutions. The US-dollar version would launch first, with the consortium flagging a euro coin as its next priority, followed by other Group of Seven currencies. Regulated experiments in cross-border stablecoin settlement are already underway elsewhere, including Visa's participation in the MAS-led BLOOM initiative.
Why the timing matters
The venture is being built deliberately around new law. In the United States, the GENIUS Act, the first federal framework for payment stablecoins, enacted in 2025, sets out who may issue a stablecoin and requires full backing by cash and short-dated government paper, along with reserve and disclosure obligations. In Europe, the Markets in Crypto-Assets regulation (MiCA) does similar work. The consortium says the initiative is intended to comply with both regimes, as applicable.
That regulatory clarity is what makes a bank-led coin commercially viable. Until stablecoin issuance had a clear legal home, large regulated institutions had little appetite to put their balance sheets near it. With a rulebook in place, the pitch changes: a stablecoin the consortium says would meet the compliance, governance, and reserve-management standards expected of a regulated bank, positioned to go head to head with established issuers such as Tether and Circle, which together dominate the market today.
The compliance questions that follow
For risk and compliance functions, the structure raises as many questions as it answers. Issuing through a separate company rather than from any single member's balance sheet is itself a governance choice. The statement does not say who will own or control that company, and with twenty-one institutions across multiple jurisdictions behind it, supervisors will want to settle where control and liability ultimately sit.
The cross-border ambition compounds the challenge. An issuer running a US-dollar coin under the GENIUS Act and a separate euro coin under MiCA will have to reconcile two frameworks that are aligned in spirit but different in detail. The industry has already warned that diverging stablecoin rules threaten tokenisation itself. How the consortium squares those regimes, and how supervisors on both sides respond to a systemically significant bank-backed issuer, will be one of the defining regulatory stories of the next eighteen months. The Bank of England and the FCA have set out a joint rulebook for systemic stablecoins, which gives some indication of the standard an issuer of this scale can expect to meet.